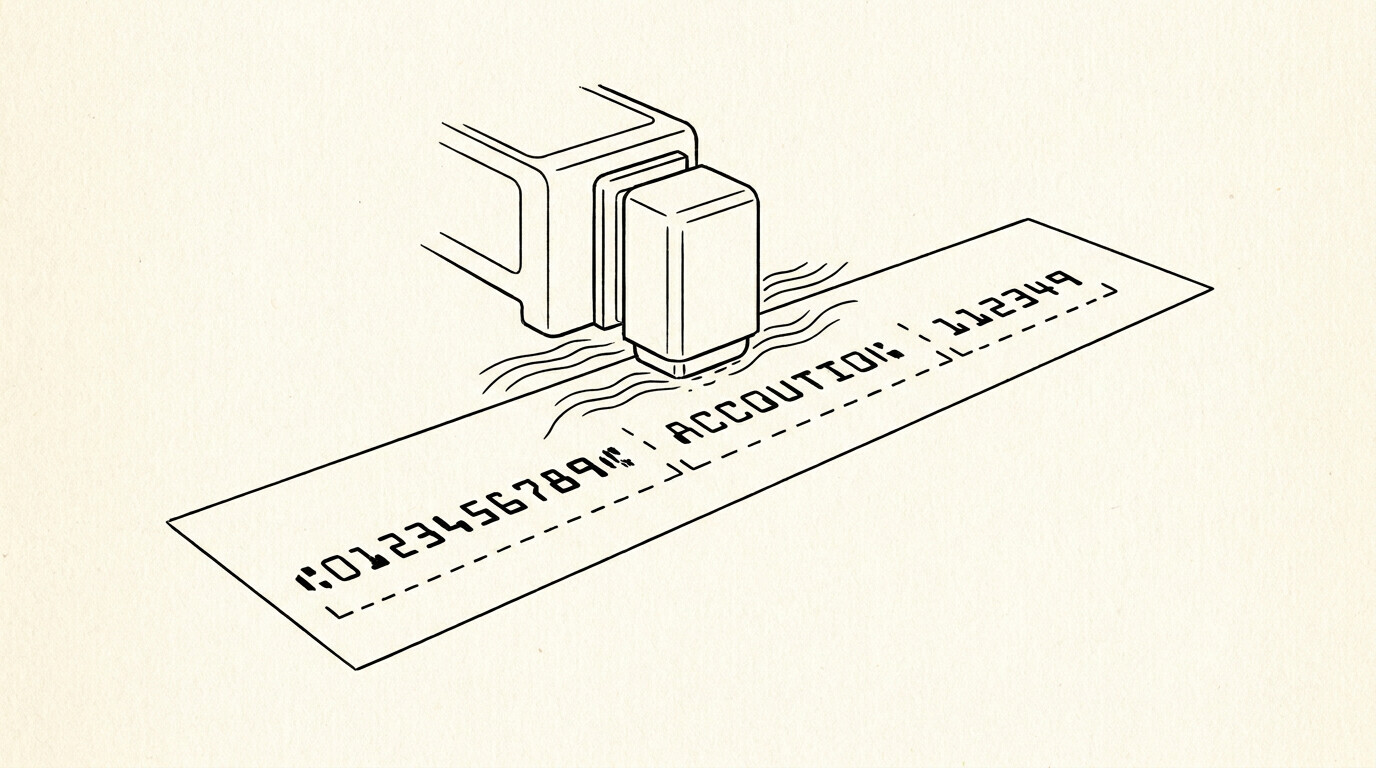

MICR (Magnetic Ink Character Recognition) lines work by encoding the routing number, account number, and check number in magnetic ink at the bottom of every
The E-13B font is the US standard for MICR characters, with 14 unique symbols (10 digits + 4 special characters).
This page covers how MICR lines work: the E-13B font, the magnetic ink technology, the 3 pieces of information in the line (routing, account, check number), how the bank’s processing machines read the line, the speed and reliability advantage over OCR, and the 3 common MICR edge cases. For the broader bank statement context, see the bank statement anatomy and the bank statement glossary.
TL;DR. MICR lines work by encoding characters in magnetic ink at the bottom of checks, then reading them with magnetic read heads in the bank’s processing machines. The E-13B font has 14 unique symbols (10 digits + 4 special characters). The 3 pieces of information: routing number (9 digits, identifies the bank), account number (10-12 digits, identifies the specific account), and check number (4 digits). The magnetic read head detects the magnetic field of each character, converts it to a digital value, and uses the routing number to route the check to the correct bank. MICR is faster and more reliable than OCR, which is why it has been the standard for 70+ years. The 3 edge cases: damaged MICR lines, non-magnetic ink (home-printed checks), and counterfeit checks with non-magnetic ink.
How MICR Lines Work: The E-13B Font
The E-13B font is the US standard for MICR characters. It was developed in the 1950s by the American Bankers Association and has been the standard since. The font defines 14 unique character shapes: 10 digits (0-9) and 4 special symbols. Each character has a unique shape, but more importantly, each character has a unique magnetic signature that the bank’s processing machines can detect.
What most guides miss about this workflow is that the quality depends on the mechanism, not on the tool. Two tools that look different on the surface often run the same 4-step process underneath: read, find, parse, verify. The difference is in how well each step handles edge cases (merged cells, missing balances, non-standard date formats, scanned vs digital input). Choosing between tools based on UI alone misses the actual quality lever.
The 4 special symbols are: the transit symbol (a vertical line with 2 horizontal bars, separates the routing number from the account number), the on-us symbol (a vertical line with 1 horizontal bar, separates the account number from the check number), the amount symbol (a vertical line with a small notch, marks where the amount is encoded if present), and the dash symbol (separates sections of the routing number on some checks). These symbols are not alphanumeric; they are structural markers that the machine uses to parse the line.
The E-13B font is proprietary to the American Bankers Association, and the character shapes are designed for both visual recognition and magnetic detection. The font was chosen because each character has a unique magnetic signature, which means the bank processing machine can reliably distinguish a “0” from a “1” or an “8” even when the check is damaged, smudged, or stamped over. This is the core advantage of MICR over OCR: magnetic reading is more reliable than optical recognition in the high-speed, high-volume check processing environment.
How the Bank Processing Machines Read MICR
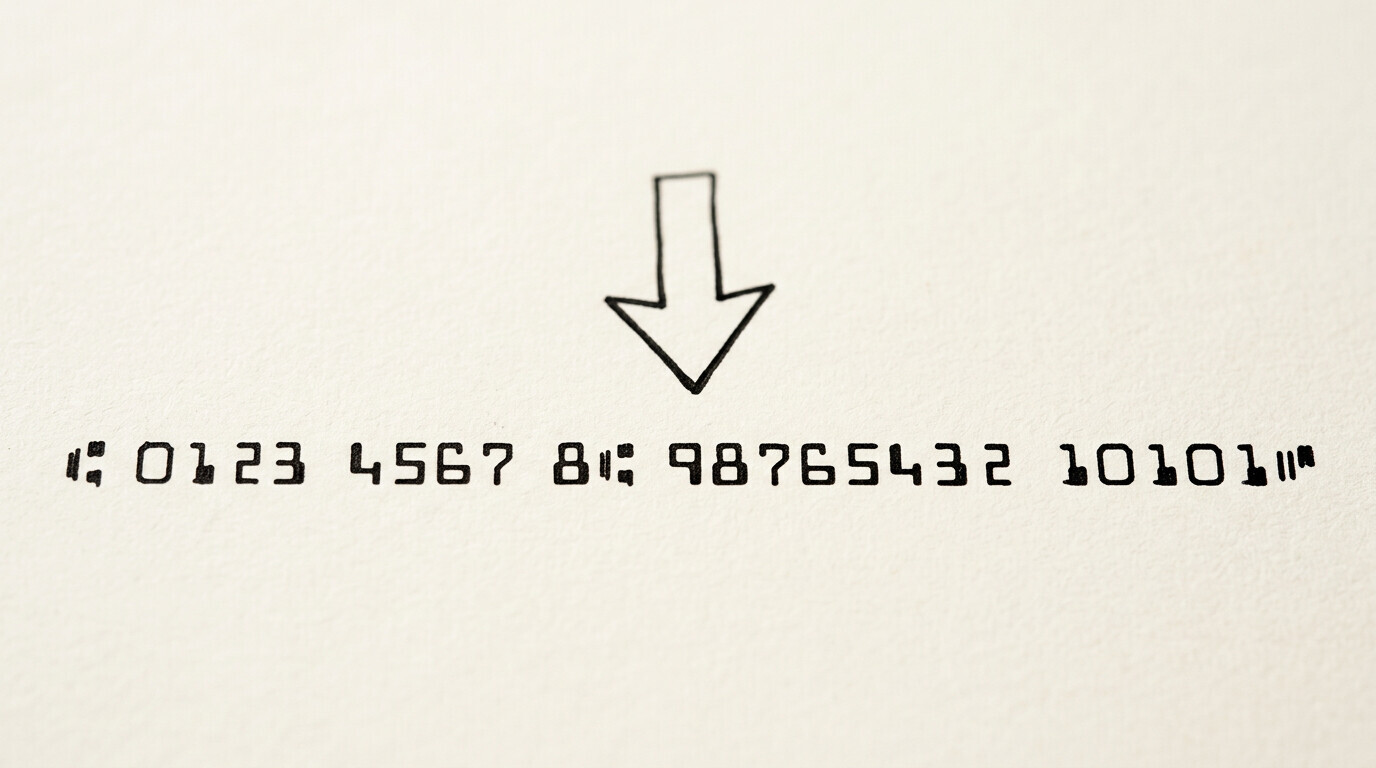
Bank processing machines read MICR lines at high speed, typically thousands of checks per hour per machine. The machine has a magnetic read head (similar to a tape recorder head) that detects the magnetic field of each character as the check moves through the machine. The read head produces an analog signal that is converted to a digital value, which is then matched against the E-13B character set to determine the digit or symbol.
The reading process has 4 steps: (1) the check is fed into the machine and transported past the read head at a controlled speed, (2) the read head detects the magnetic field of each character, (3) the analog signal is converted to a digital value, (4) the digital value is matched against the E-13B character set to determine the digit or symbol. The whole process takes milliseconds per character, which is how the machine can process thousands of checks per hour.
The machine also validates the data: it checks the routing number checksum, verifies the account number format, and confirms the check number matches the printed check number. If any validation fails, the check is routed to a manual review queue where a human reads the visible numbers and enters them into the system. The check is processed, just with a delay of 1-2 days.
From Bank Statement to QuickBooks-Ready File
That manual cleanup you just read about? This tool skips it. Turn your PDF into QBO for QuickBooks without storing your data anywhere.
Start ConvertingThe 3 Pieces of Information in the MICR Line
The MICR line encodes 3 pieces of information in a specific order, separated by special symbols:
1. Routing number (9 digits). The bank’s ABA routing number, which identifies the bank in the Federal Reserve system. The routing number is the first 9 digits after the transit symbol. The format: first 2 digits = Federal Reserve district, next 2 = specific bank, 5th digit = Federal Reserve branch, last 4 = specific bank office. For the routing number details, see the routing number definition.
2. Account number (10-12 digits). The customer’s account number at the bank, which identifies the specific account that will be debited when the check is processed. The account number is set by the bank, and the length varies. The account number is sensitive: anyone who has the routing number AND the account number can initiate an ACH debit from the account.
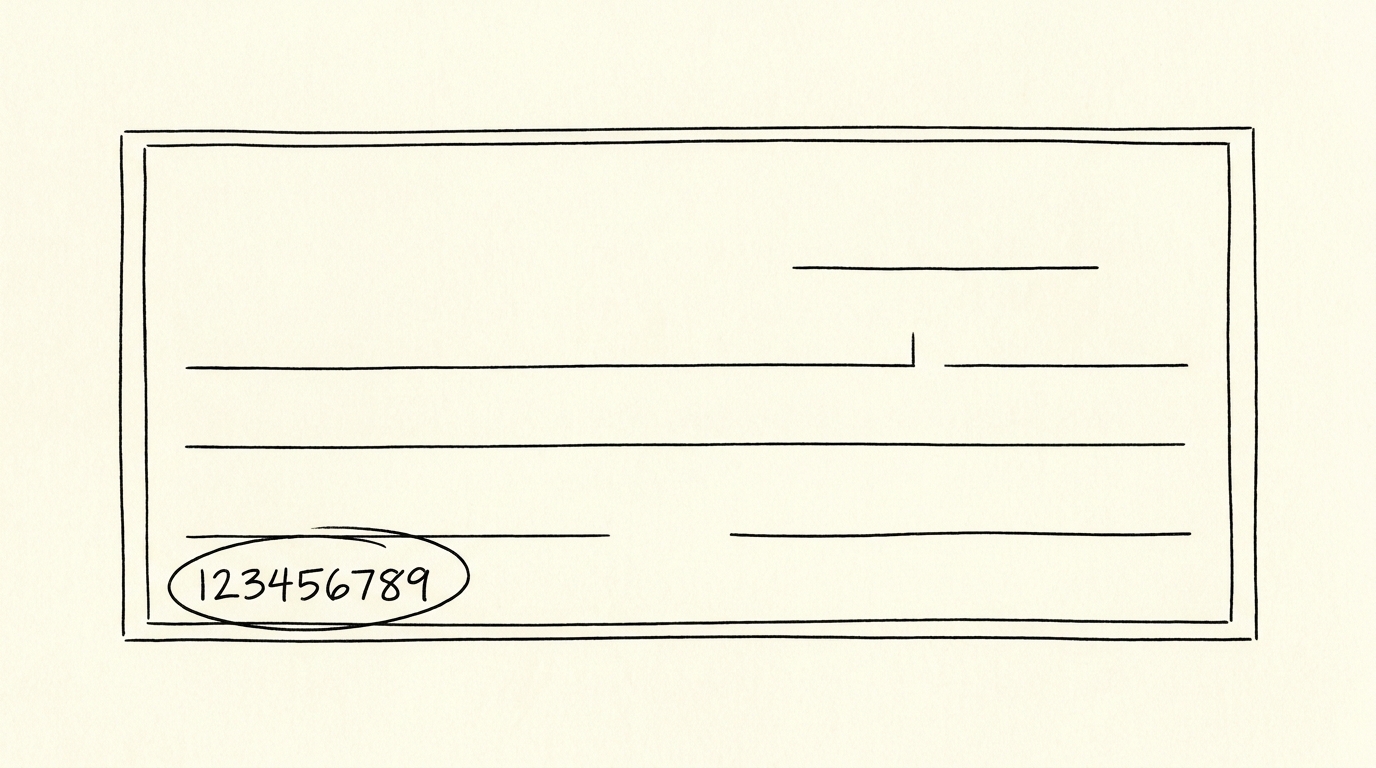
3. Check number (4 digits). The sequential number of the check, which matches the check number printed in the top right of the check. The check number is used to track the check through the processing system and to match the check to the customer’s records. For the customer’s check register, the check number is the cross-reference.
On some checks, particularly commercial checks printed by accounting software, the amount of the check is also encoded in the MICR line at the “amount symbol” position. This is called the “carriage return” position. The amount encoding is optional and is more common on commercial checks than personal checks. For personal checks, the amount is read by OCR or MICR after the check is signed and the amount is written in.
Why Magnetic Ink, Not Regular Ink
Magnetic ink is required because the US check processing system processes over 11 billion checks per year at speeds of thousands per hour per machine. Optical recognition (OCR) at those speeds is unreliable because check surfaces vary (some glossy, some matte, some with watermarks, some with backgrounds), and OCR errors are unacceptable for financial transactions. Magnetic reading, by contrast, is reliable because the magnetic property is independent of the visual surface, which is why the MICR line can be read even when the check is stamped, signed, marked, or has a coffee stain on it.
The cost of magnetic ink is higher than regular ink, which is why only the MICR line uses it. A standard check has the rest of the text printed in regular ink (the payee line, the date line, the signature line, the memo line, the bank name and logo). Only the bottom MICR row uses the special magnetic ink. For business checks printed in volume, MICR toner cartridges and MICR-specific printers are required to produce a machine-readable line.
Counterfeit checks are a related concern. Most counterfeit checks use regular ink to fake the MICR line, which the bank’s processing machine detects immediately because the magnetic read head cannot sense the field. The check is rejected and routed to a manual review queue. This is why even a visually perfect counterfeit check is almost always caught at the first
processing step, which matters because it limits t he practical value of check fraud to the small window before the check is processed.
The 3 Common MICR Edge Cases
3 edge cases that can disrupt MICR line reading:
1. Damaged or faded MICR. Checks that have been through the wash (literally, accidentally put through a washing machine) often have a faded or smudged MICR line. The magnetic ink can lose its magnetic properties if the check is exposed to a strong magnetic field (speakers, magnetic clasps, industrial equipment). Damaged MICR lines are sent to a manual review queue where a human reads the visible numbers and enters them into the system. The check is processed, just with a delay of 1-2 days.
2. Non-magnetic ink. Some inkjet printers and most home printers do not use true magnetic ink, so home-printed checks (used by some small businesses) may not have a magnetically readable MICR line. Banks that accept home-printed checks typically have a manual review process for them, which adds processing time. For business checks printed in volume, MICR toner cartridges and MICR-specific printers are required to produce a machine-readable line.
3. Counterfeit checks with non-magnetic ink. As mentioned above, counterfeit checks almost always have a non-magnetic MICR line, which the bank’s machine detects at processing. The check is rejected and routed to the fraud department. This is one of the reasons check fraud is rare at scale: even visually convincing counterfeits fail at the first machine-read step.
MICR and the Bank Statement
The MICR line does not typically appear on the bank statement itself, but the information encoded in the MICR line does. The bank statement shows the routing number at the top (in the account holder information section) and the account number on each transaction line or in the account summary section. For any check that cleared during the statement period, the bank statement may show an image of the check with the MICR line visible, which is useful for bookkeepers and loan officers verifying the account.
For a bookkeeper reconciling the statement, the routing number and account number on the statement should match the customer’s records. A mismatch can indicate a fraudulent statement (where the numbers were changed to redirect funds) or a bank merger (where the routing number changed but the account number stayed the same). For the full reconciliation process, see the bank statement reconciliation page and the bank statement conversion checklist.
A common failure mode bookkeepers report is treating this as a single operation rather than a chain of dependent steps. The temptation is to find a tool that ‘just works’ and stop investigating the mechanism. The result is a wrong-fix cycle: the tool gives partial output, the bookkeeper spends 30+ minutes troubleshooting, the fix is for the wrong step, and the same error recurs on the next statement. The fix: identify which step failed and apply the right intervention to that step.
Start with the Workflow
The fastest path is to start with the conversion step, which produces the data that every other step needs. The bank statement converter handles the PDF-to-Excel step in 2-5 minutes, with no upload to a server.
For a complete reference of the terms used throughout this article, see the bank statement glossary.
For deeper understanding, see: How Micr Line Mechanism Deep.
From PDF to Excel in one click
Forget retyping line by line. Upload any bank statement, get a spreadsheet you can actually use. Your files are never stored, and you can test the converter with 3 free conversions.
Try it free