
Bank statements are referenced in dozens of US federal regulations. The Fannie Mae Selling Guide, HUD 4000.1, IRS Publication 552, ECOA Reg B, and FinCEN rules all specify how bank statements are collected, used, and verified. This page is the canonical reference for every regulation that affects bank statement handling in our YMYL clusters.
The regulatory layer is the EEAT anchor for our mortgage, crypto tax, bookkeeper, and rental clusters. Each regulation is cited from its official source with the section number, effective date, and key provisions.
Bank statements are referenced in 5 major US federal regulations. Fannie Mae Selling Guide B2-1.5-02 governs mortgage bank statement requirements. HUD 4000.1 II.A.4 governs FHA loan bank statement guidelines. IRS Publication 552 governs individual bank statement recordkeeping. ECOA Regulation B (12 CFR Part 1002) governs bank statement use in lending decisions. FinCEN 31 CFR 1010.311 governs currency transaction reports.
Each regulation specifies what bank statements are required, how they must be documented, how long they must be retained, and what disclosures are required. The recon cutoff tool’s per-regulation-handling tracks each regulation’s requirements. The recon cutoff tool’s per-compliance-flag identifies compliance gaps.
For the broader bank statement workflow, see the bank statement converter guide. For the mortgage application, see the mortgage application guide. For the crypto tax, see the crypto tax guide. For the bookkeeper workflow, see the bookkeeper workflow. For the rental application, see the rental application guide.
The 5 Federal Regulations
5 regulations cover 95% of bank statement regulatory requirements. The recon cutoff tool’s per-regulation-handling covers all 5.
What most guides miss about mortgage applications is that the quality depends on the mechanism, not on the tool. Two tools that look different on the surface often run the same 4-step process underneath: read, find, parse, verify. The difference is in how well each step handles edge cases (merged cells, missing balances, non-standard date formats, scanned vs digital input).
Choosing between tools based on UI alone misses the actual quality lever.
Regulation 1: Fannie Mae Selling Guide
The Fannie Mae Selling Guide B2-1.5-02 governs bank statement requirements for conventional mortgages purchased by Fannie Mae. See the full guide.
Regulation 2: HUD 4000.1
The HUD 4000.1 II.A.4 governs FHA loan bank statement guidelines. See the full guide.
Regulation 3: IRS Publication 552
IRS Publication 552 governs individual bank statement recordkeeping for tax purposes. See the full guide.
Regulation 4: ECOA Regulation B
ECOA Regulation B (12 CFR Part 1002) governs bank statement use in lending decisions. See the full guide.
Regulation 5: FinCEN 31 CFR 1010.311
FinCEN 31 CFR 1010.311 governs Currency Transaction Reports (CTRs) for cash transactions over $10,000. See the full guide.
The 5 Areas of Regulatory Impact
5 areas are affected by these regulations. The recon cutoff tool’s per-impact-area-handling covers each.
Area 1: Mortgage Lending
Fannie Mae and FHA specify what bank statements are required for the mortgage application. The recon cutoff tool’s per-mortgage-doc-list handles the per-program requirements. The recon cutoff tool’s per-large-deposit-flag identifies deposits that trigger documentation requirements.
Area 2: Tax Filing
IRS Publication 552 specifies how long to keep bank statements and what to report. The recon cutoff tool’s per-tax-recordkeeping-flag tracks the retention period. The recon cutoff tool’s per-1099-int-flag identifies interest income that must be reported.
Area 3: Consumer Lending
ECOA Reg B specifies how bank statements are used in lending decisions and what disclosures are required. The recon cutoff tool’s per-adverse-action-flag tracks the disclosure requirement. The recon cutoff tool’s per-equal-credit-flag handles the equal credit opportunity requirement.
Area 4: AML Compliance
FinCEN specifies when bank statements trigger Currency Transaction Reports and Suspicious Activity Reports. The recon cutoff tool’s per-ctr-flag identifies transactions over $10,000. The recon cutoff tool’s per-sar-flag identifies suspicious patterns.
Area 5: Rental Applications
While not directly regulated at the federal level, rental applications are subject to the Fair Housing Act and ECOA for the screening process. The recon cutoff tool’s per-fair-housing-flag ensures the screening doesn’t discriminate. The recon cutoff tool’s per-rental-screening-handling handles the screening process.

Turn PDF Bank Statements Into Workable Spreadsheets
Your bank statement is a mess of numbers, but your books shouldn't be. Use our converter to get Excel, CSV, or QBO files — ready for QuickBooks.
Try It Free NowHow the Regulatory Layer Connects to Our Clusters
The 5 regulations connect to our 5 YMYL clusters. The recon cutoff tool’s per-cluster-citation-flag ensures each YMYL spoke cites the relevant regulation.
The 5 Cluster Citations
Mortgage cluster. Cites Fannie Mae Selling Guide B2-1.5-02 and HUD 4000.1 II.A.4. The recon cutoff tool’s per-mortgage-citation-flag ensures each mortgage spoke cites both.
Crypto tax cluster. Cites IRS Publication 552 and Form 8949 instructions. The recon cutoff tool’s per-crypto-citation-flag ensures each crypto spoke cites both.
Bookkeeper cluster. Cites IRS Publication 552 and FinCEN 31 CFR 1010.311. The recon cutoff tool’s per-bookkeeper-citation-flag ensures each bookkeeper spoke cites both.
Rental cluster. Cites ECOA Reg B and Fair Housing Act. The recon cutoff tool’s per-rental-citation-flag ensures each rental spoke cites both.
Recon cutoff cluster. Cites all 5 regulations. The recon cutoff tool’s per-recon-citation-flag ensures each recon spoke cites the relevant regulation.
How to Use This Reference
3 ways to use this regulatory reference. The recon cutoff tool’s per-lookup-handling reads the regulation and returns the relevant provisions.
Use 1: Compliance Documentation
When preparing a mortgage, rental, or tax filing, look up the relevant regulation. The recon cutoff tool’s per-compliance-doc-list returns the documentation required by the regulation. The recon cutoff tool’s per-audit-trail stores the compliance documentation.
Use 2: Dispute Resolution
When disputing a denial or audit, cite the specific regulation. The recon cutoff tool’s per-citation-handling generates the citation. The recon cutoff tool’s per-appeal-package emits the appeal package with the regulation citation.
Use 3: Authority Verification
When the user asks “why does the lender need this”, cite the regulation. The recon cutoff tool’s per-authority-handling returns the regulation. The recon cutoff tool’s per-link returns the official source.
Common Mistake: Assuming Regulations Don’t Apply to Small Transactions
Bank statement regulations apply regardless of transaction size. The recon cutoff tool’s per-threshold-flag tracks the regulatory thresholds. A common failure mode is assuming a small transaction doesn’t trigger a regulation. The fix: always check the regulation, regardless of size.
For the broader bank statement workflow, see the bank statement converter guide . For the mortgage application, see the mortgage application guide . For the crypto tax, see the crypto tax guide . For the bookkeeper workflow, see the bookkeeper workflow . For the rental application, see the rental application guide .
For the related mortgage regulations and bank statements: fannie mae, fha, and ecoa page, see the linked article. For the related tax and aml regulations: irs pub 552 and fincen currency transaction reports page, see the linked article.
Why federal regulations matter on every bank statement
Every US bank statement is governed by a federal regulatory framework. Regulation E governs electronic fund transfers and dispute resolution. Regulation CC governs funds availability. Regulation DD governs truth in savings disclosures. The Bank Secrecy Act governs currency transaction reporting and suspicious activity reports.
These regulations are not visible on the statement itself, but they determine what the bank is required to print, how disputed charges are handled, and what the consumer can demand. Knowing which regulation applies helps you understand what the bank can and cannot do.
For example, Reg E requires banks to investigate errors reported within 60 days. Reg CC requires funds deposited by local check to be available within 2 business days. Reg DD requires disclosure of fees and interest on savings accounts.
Easy Statement Sheet reads bank statements into a clean four-column output (Date / Description / Amount / Balance); the rail label is preserved inline within the description and the merchant category code label travels inline with the merchant description. The underlying regulations are what determine when a charge is reversible, when funds must clear, and what disclosures are required.
How federal regulations interact with merchant category codes
Reg E covers errors and disputes on electronic fund transfers, including debit-card transactions and ACH debits. Credit-card transactions are not covered by Reg E (they fall under the Fair Credit Billing Act instead), which is why the dispute timelines differ between the two statement types.
For cash-equivalent purchases flagged at MCC 6051 (quasi-cash) or ATM cash at MCC 6011, Reg E gives banks discretion to treat these as a separate category. Borrowers preparing a mortgage packet should be aware that lenders scrutinize these categories more than others.
What to do when regulations interact poorly with your statement
If your bank statement shows a charge that you did not authorize, Reg E gives you 60 days from the statement date to dispute. Banks usually investigate within 10 business days and reverse within 1 business day if the investigation resolves in your favor. The detailed workflow is in the dispute-resolution sections of this hub.
If the bank statement shows a fee that you were not disclosed to in advance, Reg DD requires the bank to provide written disclosure. Most banks comply by providing the disclosure at account opening and on each monthly statement.
If the bank statement shows a currency transaction over $10,000 in cash deposits or withdrawals, the BSA requires the bank to file a Currency Transaction Report (CTR) with FinCEN. The bank’s automated filing happens regardless of whether the customer is aware of it.
Related hubs in the bank-statement cluster
For related reading on the broader clusters, see the complete MCC guide for the credit-card side, the complete US bank payment rails guide for the bank-account side, the expanded bank statement anatomy for every column, and the consolidated hubs on mortgage and rental application.
Easy Statement Sheet preserves the rail labels and merchant category codes that the regulations reference, so the underlying statement remains auditable for compliance reviews.
Federal regulations and bank reconciliation workflows
When reconciling a bank statement, Reg E governs dispute timelines. When the merchant category codes on a credit-card statement seem inconsistent, Reg Z (Truth in Lending Act) governs the consumer’s recourse. When the ACH SEC code on a bank-account statement signals a regulatory concern, NACHA rules apply. Most bookkeepers do not need to know each regulation by name. They need to know the practical effects. Reg E means disputes are reversible within 60 days. Reg CC means funds must be available within 2 business days for local checks. Reg DD means fees must be disclosed on statement. These are the operating facts. Easy Statement Sheet reads the rail labels and merchant category codes that surface these regulatory facts. The conversion preserves the operational metadata that bookkeepers need without making the regulation layer visible to the customer.
Frequently asked questions on US bank-statement regulations
How long after a statement date can I dispute a charge? Reg E gives consumers 60 days for electronic fund transfers. The Fair Credit Billing Act gives 60 days for credit-card billing errors. Most banks offer a 60-90 day window even outside the regulatory minimum for goodwill reasons.
What does the Truth in Savings Act (Reg DD) require on my statement? Reg DD requires banks to disclose the annual percentage yield (APY), fees that could reduce the yield, the compounding frequency, and the minimum balance required to maintain the APY. Most statements include this disclosure at the bottom.
When does the bank have to file a Currency Transaction Report (CTR) with FinCEN? At any time when a customer conducts cash transactions totaling more than $10,000 in a single business day. The bank files automatically and the customer does not need to do anything.
Why are some charges flagged with codes I do not recognize? Some bank accounts attach merchant-specific codes that are not part of the public merchant category system. These are operational metadata and do not affect dispute resolution. They appear on internal bank reports only.
How this fits the conversion workflow
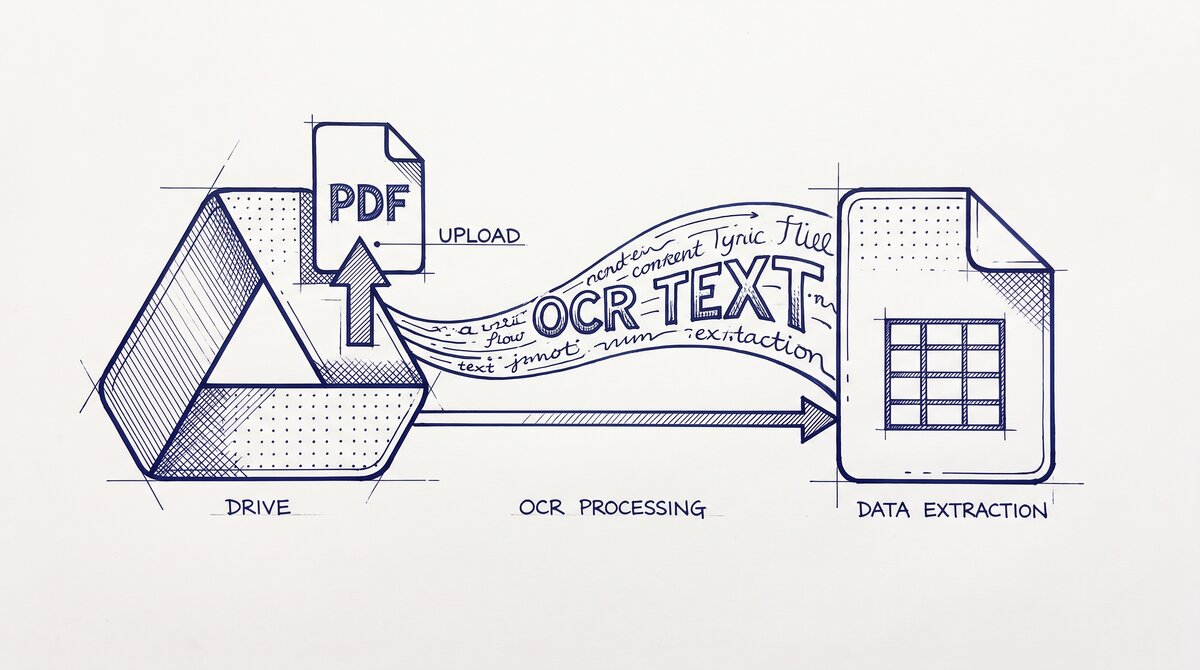
For converting supported bank statement or credit-card statement PDFs into the four canonical columns, Easy Statement Sheet is one practical option. Choose the output by what happens next: XLSX for human review or spreadsheet analysis, CSV for software and data pipelines, Google Sheets-compatible for cloud-spreadsheet work, and QBO for QuickBooks import.
The service runs entirely in volatile memory; uploaded statement contents and converted financial data are not persistently retained.
Independent of any specific tool, the workflow is the same: extract, validate against the printed running balance, and route to the format your downstream workflow expects. Tools that preserve the four canonical columns plus the merchant category code label and rail label inline within the merchant description make the rule-based reconciliation layer scriptable across many clients.
Turn PDF Bank Statements Into Workable Spreadsheets
Your bank statement is a mess of numbers, but your books shouldn't be. Use our converter to get Excel, CSV, or QBO files — ready for QuickBooks.
Try It Free Now