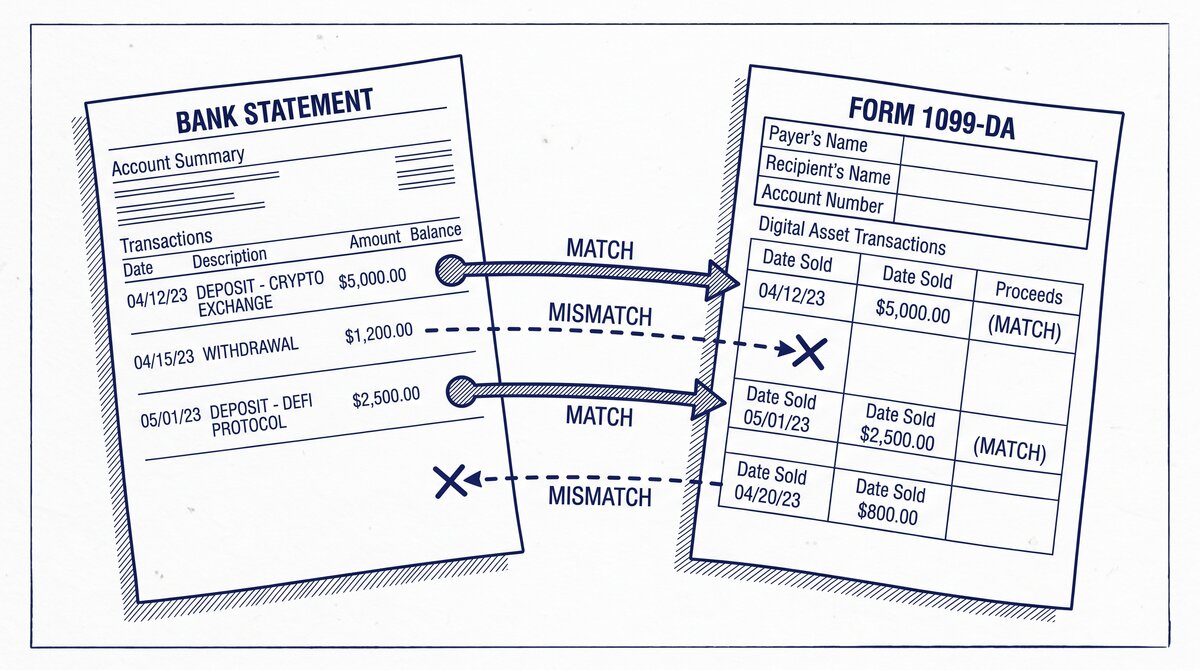

1099-DA reports the broker-side data (gross proceeds, cost basis, transaction type). The bank statement reports the cash settlement. For sales, these should match within a few days and a few dollars. For transfers, the 1099-DA may report nothing while the bank statement shows no cash (a transfer is not a taxable event, but a missing broker record is a red flag).
The reconciliation workflow catches the 3 common mismatches: timing, fees, and missing transactions.
The 4 Reconciliation Patterns
1099-DA entries fall into 4 patterns when reconciled with a bank statement. Each pattern has a different matching rule.
Pattern 1: Sale (Crypto for Fiat)
The 1099-DA reports gross proceeds and cost basis. The bank statement shows a corresponding deposit from the exchange to the user’s bank account within 1-3 business days. The amounts should match within a small margin for fees and exchange rate fluctuations.
Example: 1 BTC sold at $50,000, broker fee $25. 1099-DA Box A: $50,000. Bank statement: deposit of $49,975 (less the $25 fee). The 1099-DA reports gross; the bank statement reports net. The user reconciles by subtracting the broker fee.
Pattern 2: Transfer (Wallet to Wallet)
The 1099-DA may report the transfer (Box C = T, transaction type transfer). The bank statement shows nothing because no cash moved. The 1099-DA cost basis is the same as the gross proceeds (no gain or loss on a transfer).
This pattern is a reconciliation no-op: the 1099-DA reports, the bank statement is silent, and the user does not report a gain or loss on Form 8949.
Pattern 3: Staking Reward or Airdrop
The 1099-DA reports the reward as ordinary income at fair market value on the day received (Box C = O, Box A = FMV). The bank statement shows nothing at the time of the reward because the crypto is in the user’s wallet, not the bank.
The bank statement shows cash only when the user sells the reward for fiat. At that point, the 1099-DA reports a separate sale entry (the original receipt is one entry, the sale is another). The user reports both on Form 8949: the receipt as ordinary income, the sale as capital gain.
Pattern 4: Exchange (Crypto for Crypto)
The 1099-DA reports the fair market value of the crypto received as gross proceeds. The bank statement shows nothing because no fiat cash moved. The exchange is reported as a taxable event (the user disposed of one crypto and acquired another).
This pattern requires careful cost basis tracking. The user has to know the cost basis of the disposed crypto (to calculate the gain) and the fair market value of the received crypto (to establish the new cost basis).
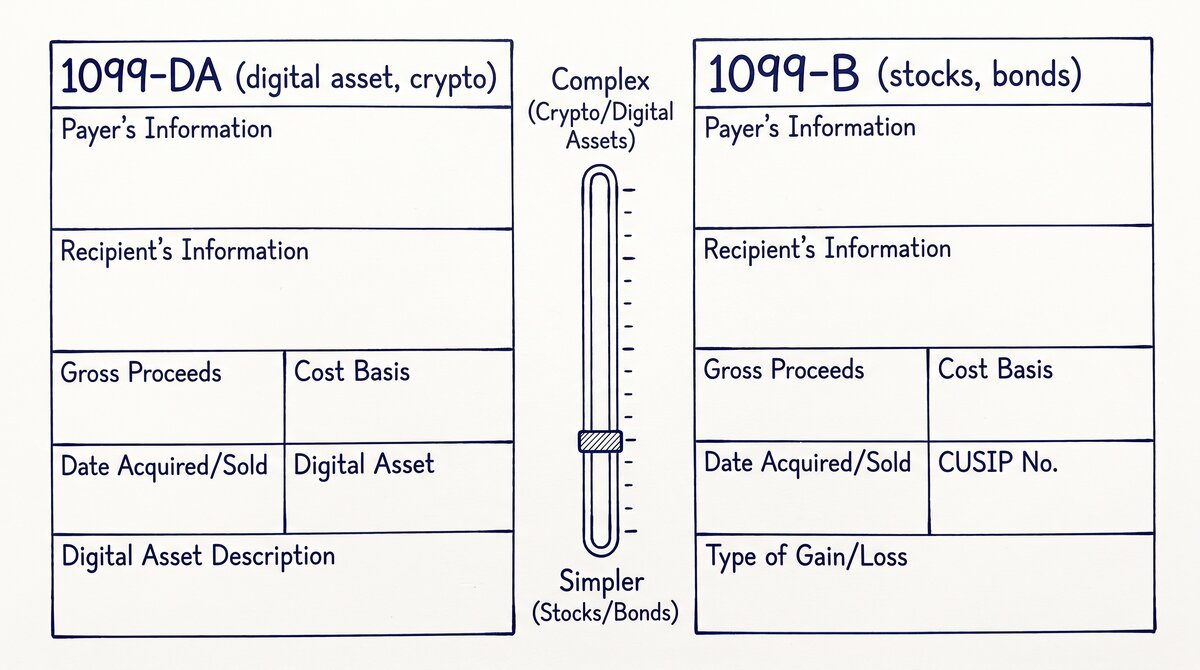
Where the 1099-DA and Bank Statement Agree (and Where They Differ)
Where They Agree
- Sale amounts within 1-3% (after broker fees)
- Timing within 1-3 business days
- Net deposits (gross proceeds minus broker fees)
Where They Differ
- Timing: a sale on Friday may not settle until Monday or Tuesday. The 1099-DA reports Friday, the bank statement shows Monday.
- Fees: the 1099-DA reports gross proceeds; the bank statement shows net deposit. The difference is the broker fee.
- Exchange rate: for non-USD sales, the 1099-DA reports USD value at the time of sale, the bank statement may show USD equivalent at the time of deposit. The difference is the FX rate movement.
- Stablecoin: 1099-DA may report a stablecoin sale as a transaction; the bank statement may not (if the stablecoin never left the exchange’s ecosystem).
- DeFi: 1099-DA does not cover DeFi transactions; the bank statement may show nothing for a DeFi swap.
From PDF to Excel in one click
Forget retyping line by line. Upload any bank statement, get a spreadsheet you can actually use. Your files are never stored, and you can test the converter with 3 free conversions.
Try it freeThe 3 Common Mismatches and How to Find Them
Mismatch 1: Timing
The 1099-DA reports a sale on December 28. The bank statement shows the corresponding deposit on January 2. The user has to find the January deposit to match the December sale.
How to find it: search the bank statement for the deposit amount matching the 1099-DA amount, allowing for fees and FX. Mark the match. If no match is found, flag for review.
Mismatch 2: Fees
The 1099-DA reports $50,000. The bank statement shows $49,500. The $500 difference is the broker fee. The user reconciles by noting the fee and matching the net amount.
How to find it: check the broker’s fee schedule or the confirmation email for the sale. Most exchanges have a flat fee or a percentage fee that is deducted from the gross proceeds.
Mismatch 3: Missing Transactions
The user sold crypto on a non-US exchange (Binance, Kraken International). The 1099-DA does not cover non-US brokers. The bank statement shows the deposit. The user has to self-report the sale on Form 8949.
How to find it: reconcile the bank statement against all exchanges used, not just US-based ones. The user has to maintain a separate record of non-US transactions.
When a Mismatch Triggers an IRS Audit
The IRS uses automated matching to flag mismatches between 1099-DA and Form 8949. The thresholds:
- Mismatch under 5%: usually cleared without review
- Mismatch 5-10%: may trigger a notice (CP2000) asking for clarification
- Mismatch over 10%: likely audit trigger; the user has to provide documentation
- Mismatch over 25%: high probability of audit; the user has to provide documentation and may face penalties
The mismatch is calculated on the gross proceeds reported, not the net deposit. A $50,000 1099-DA entry with a $40,000 bank statement deposit (20% mismatch) is more likely to trigger audit than a $5,000 entry with a $4,000 deposit (same 20% mismatch).
A common failure mode bookkeepers report is treating this as a single operation rather than a chain of dependent steps. The temptation is to find a tool that ‘just works’ and stop investigating the mechanism.
The result is a wrong-fix cycle: the tool gives partial output, the bookkeeper spends 30+ minutes troubleshooting, the fix is for the wrong step, and the same error recurs on the next statement. The fix: identify which step failed and apply the right intervention to that step.
The Step-by-Step Reconciliation Workflow
Collect all 1099-DA forms from each broker by January 31.
Download all bank statements for the tax year (every account that received crypto proceeds).
For each 1099-DA entry, find the corresponding bank statement line. Match on date (1-3 business days), amount (within 5%), and counterparty (the exchange name).
For each match, note the fee difference and the timing difference. Reconcile to the net deposit.
For unmatched 1099-DA entries, check for missing bank statement lines (sales that did not settle), timing mismatches (sales that settled in the next year), or non-US broker transactions (not on 1099-DA).
For unmatched bank statement deposits, check for sales on non-US exchanges, P2P sales, or sales that were not reported on 1099-DA. Self-report these on Form 8949.
Document all matches and mismatches. Save the reconciliation workpaper with the tax return.
The 1099-DA pillar covers the form’s anatomy. The 1099-DA vs 1099-B sub-pillar covers the form differences. The cost basis methods spoke covers FIFO and Spec ID. The broker reporting requirements spoke covers who counts as a broker and the phased rollout. For the related crypto tax forms: 1099-da, form 8949, and schedule d page, see the linked article.
For a deeper understanding, see: crypto tax statement pillar . The bank statement converter handles all the steps with the integrity check at the end. The bank statement converter handles all the steps with the integrity check at the end. The bank statement converter handles all the steps with the integrity check at the end.
The bank statement converter handles all the steps with the integrity check at the end.
Related: complete 1099-DA crypto tax guide
This topic is part of the broader 1099-DA and crypto-tax cluster on this site. The consolidated hub for the entire topic, including the form mechanics, broker requirements, cost basis methods, reconciling to bank statements, and state-level differences, now lives in the complete 1099-DA crypto tax reporting guide.
For related reading, the complete US bank payment rails guide covers ACH and wire cash flows from crypto exchanges, and the complete MCC guide covers merchant category codes on credit-card statements. The expanded bank statement anatomy pairs naturally with this hub.
More on the broader cluster
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes.
Decision framework for this topic
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
Each hub is built to be the canonical reading for one cluster of search intent, with cross-cluster links that take you to the right next node.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal. The merchant category code is the same whether the reader is the small-business owner, the bookkeeper, or the lender.
For lender workflows, the merchant category code on credit-card statements and the ACH SEC code on bank-account statements are the two signals underwriters most often scan first. Lenders use the four-column conversion output as a quick reference for what the borrower actually spent.
Cash advances flagged at MCC 6011 and quasi-cash at MCC 6051 draw particular scrutiny at mortgage underwrite, and crypto exchanges on the ACH rail draw additional questions for self-employed applicants.
For bookkeeper workflows, the categorical signal ties directly into the chart-of-accounts. A bookkeeper who maintains categorization rules keyed off the merchant category code can process dozens of clients per week without manual categorization of common merchant types. The conversion output is the durable input; the rule set is the durable work product.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored. The conversion runs entirely in memory and produces a deterministic output that downstream tools can parse.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes. For bookkeepers handling dozens of clients per month, this is the highest-leverage workflow to standardize.
Related reading and broader clusters
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
Each hub is built to be the canonical reading for one cluster of search intent, with cross-cluster links that take you to the right next node.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal. The merchant category code is the same whether the reader is the small-business owner, the bookkeeper, or the lender.
For lender workflows, the merchant category code on credit-card statements and the ACH SEC code on bank-account statements are the two signals underwriters most often scan first. Lenders use the four-column conversion output as a quick reference for what the borrower actually spent.
Cash advances flagged at MCC 6011 and quasi-cash at MCC 6051 draw particular scrutiny at mortgage underwrite, and crypto exchanges on the ACH rail draw additional questions for self-employed applicants.
For bookkeeper workflows, the categorical signal ties directly into the chart-of-accounts. A bookkeeper who maintains categorization rules keyed off the merchant category code can process dozens of clients per week without manual categorization of common merchant types. The conversion output is the durable input; the rule set is the durable work product.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored. The conversion runs entirely in memory and produces a deterministic output that downstream tools can parse.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes. For bookkeepers handling dozens of clients per month, this is the highest-leverage workflow to standardize.
From Bank Statement to QuickBooks-Ready File
That manual cleanup you just read about? This tool skips it. Turn your PDF into QBO for QuickBooks without storing your data anywhere.
Start Converting