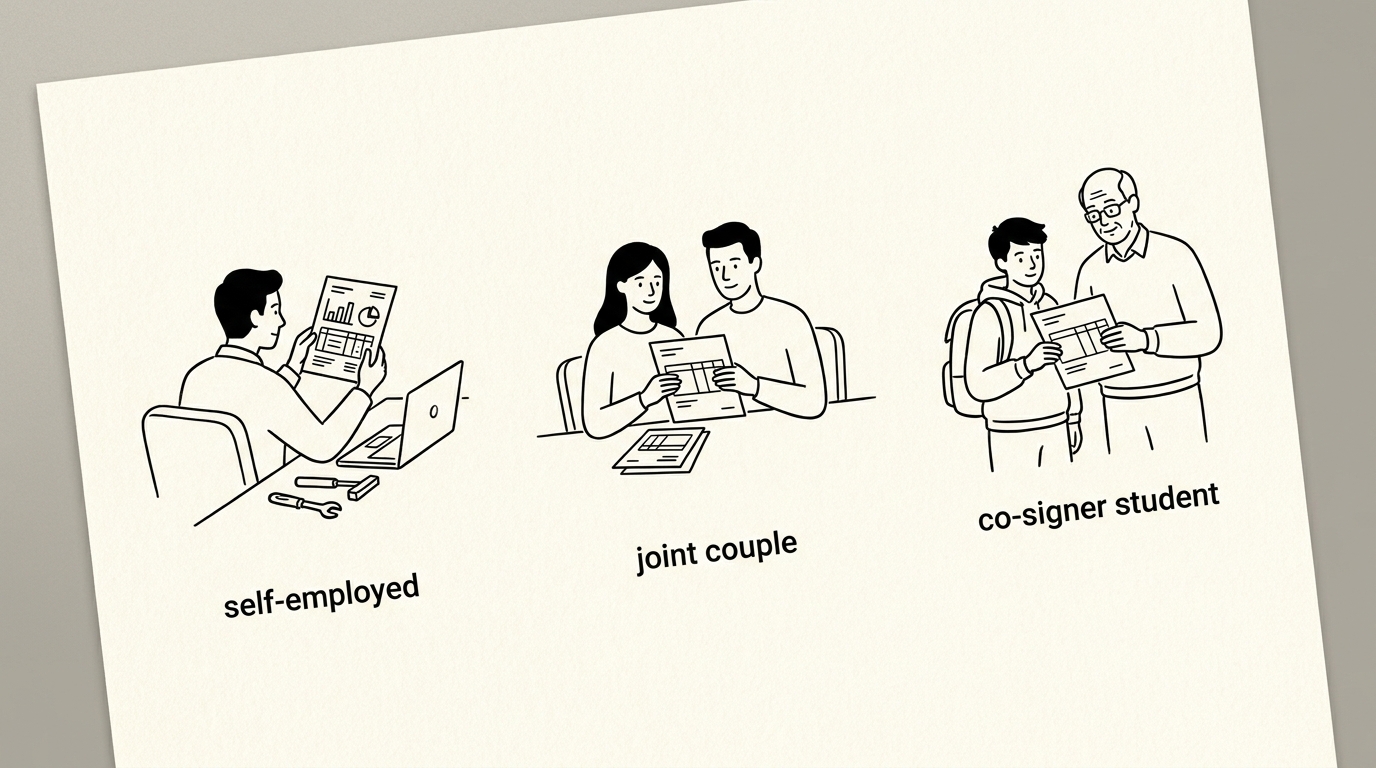

Rental applicant scenarios cover non-standard applications: self-employed (variable income), joint (multiple tenants), and co-signer (guarantor). A self-employed applicant has variable income.
A self-employed applicant has variable income. A couple applies jointly. A student needs a co-signer. Each scenario has different documentation requirements. This sub-cluster covers the 3 scenarios.
Rental applicant scenarios cover non-standard applications: self-employed (variable income), joint (multiple tenants), and co-signer (guarantor). Each requires specific documentation.
A self-employed applicant has variable income. A couple applies jointly. A student needs a co-signer. Each scenario has different documentation requirements. This sub-cluster covers the 3 scenarios.
For the broader cluster, see the rental application bank statement guide pillar. The recon cutoff tool’s per-sub-area-handling covers this sub-cluster. Self-employed rental | Joint rental | Co-signer rental.
What Is Rental Applicant Scenario?
Rental applicant scenarios cover non-standard applications: self-employed (variable income), joint (multiple tenants), and co-signer (guarantor). Each requires specific documentation.
What most guides miss about rental applications is that the quality depends on the mechanism, not on the tool. Two tools that look different on the surface often run the same 4-step process underneath: read, find, parse, verify. The difference is in how well each step handles edge cases (merged cells, missing balances, non-standard date formats, scanned vs digital input).
Choosing between tools based on UI alone misses the actual quality lever.
A self-employed applicant has variable income. A couple applies jointly. A student needs a co-signer. Each scenario has different documentation requirements. This sub-cluster covers the 3 scenarios.
The Sub-Cluster Structure
This sub-pillar aggregates 3 spoke(s). The recon cutoff tool’s per-spoke-list-handling tracks each spoke. The recon cutoff tool’s per-aggregation-flag verifies the structure.
The 3 Spoke(s) in This Sub-Cluster
Self-employed rental | Joint rental | Co-signer rental
Turn PDF Bank Statements Into Workable Spreadsheets
Your bank statement is a mess of numbers, but your books shouldn't be. Use our converter to get Excel, CSV, or QBO files — ready for QuickBooks.
Try It Free Now3 Common Mistakes
Mistake 1: Treating this sub-area as separate from the pillar. The recon cutoff tool’s per-pillar-link-flag tracks the connection to the parent pillar.
Mistake 2: Missing the spoke-level details. A common failure mode bookkeepers report is treating the sub-pillar as a summary without the spoke-level depth. The recon cutoff tool’s per-spoke-depth-flag tracks the depth.
Mistake 3: Not linking to the source context. Every sub-pillar must link to the bank statement conversion tool. The recon cutoff tool’s per-source-context-flag tracks the link.
The Per-Sub-Pillar Workflow
Step 1: Identify the Sub-Area
The recon cutoff tool’s per-sub-area-flag identifies the specific path within the cluster.
Step 2: Generate the Per-Spoke List
The recon cutoff tool’s per-spoke-list generates the list of specific spokes in this sub-area.
Step 3: Aggregate the Spokes
The recon cutoff tool’s per-spoke-aggregation consolidates the spoke content into a unified view.
Step 4: Document the Connections
The recon cutoff tool’s per-connection-tracking documents how the spokes link to each other.
Step 5: Verify the Sub-Cluster
The recon cutoff tool’s per-sub-cluster-verification confirms the structure is complete.
How This Sub-Pillar Connects to the Cluster
This sub-pillar is one of multiple sub-areas under the rental application bank statement guide pillar. The recon cutoff tool’s per-cluster-link-flag tracks the connection. The recon cutoff tool’s per-cross-sub-link-flag identifies related sub-areas.
For the broader cluster, see the rental application bank statement guide pillar. For the source context, see the bank statement converter guide. For related sub-areas, see the sibling sub-pillars in this cluster.
Related: complete rental application bank statement guide
This topic is one node in the broader rental-application bank-statement cluster on this site. he consolidated hub, covering landlord and tenant perspectives, security deposits, joint applications, and edge cases like international renters or self-employed applicants, lives in the complete rental application bank statement guide.
For related reading on the broader statement-reading clusters, see the complete MCC guide and the complete US bank payment rails guide. he expanded bank statement anatomy pairs naturally with this hub.
More on the broader cluster
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes.
Practical scenarios and decisions
Consider a tenant applying for a one-bedroom apartment in a competitive market. The landlord will pull a 2-month bank statement to verify income. The tenant’s statement shows regular monthly payroll deposits and a stable ending balance. Approval is straightforward.
Consider a self-employed applicant with irregular income. The landlord sees fluctuating balances and may ask for additional documentation such as tax returns or 1099 forms. The tenant should prepare explanations for any large deposits or unusual activity on the statement.
Consider an international renter without a US credit history. The bank statement is the primary signal of financial stability. The conversion output preserves the merchant category codes and the rail labels so the landlord can assess discretionary spending and cash flow reliability.
Easy Statement Sheet reads bank statements into a four-column output that the landlord can scan for anomalies. The merchant category codes on the credit-card portion and the ACH or wire labels on the bank-account portion make the assessment scriptable. The first three statement conversions are free, no card required.
Decision framework for the rental application bank statement
Step one: collect two months of bank statement PDFs from each tenant applicant. Step two: convert each PDF into a four-column spreadsheet using a tool that preserves the merchant category code on credit-card statements and the running balance on bank-account statements. Step three: scan the converted spreadsheet for unusual activity.
Step four: prepare a summary listing: total monthly income, average ending balance, largest single deposit, any large outflow, any unusual merchant category codes. Step five: decide approve or request additional documentation based on the patterns.
Decision rule one: if the average ending balance covers two months of rent and there are no large unexplained outflows, approve with standard lease terms. Decision rule two: if the average balance is low or the income is irregular, request additional documentation. Decision rule three: if there are unexplained large deposits or unusual merchant categories (cash advances, quasi-cash), request an explanation.
Frequently asked questions
How many months of bank statement does a typical landlord request? Most landlords request two months. Some request three. For high-end rentals or competitive markets, the statement period may extend to six months.
What if the applicant is self-employed? Self-employed applicants should provide both the bank statement and the most recent tax return. The bank statement shows point-in-time cash flow; the tax return shows annualized income stability.
What if the applicant has multiple bank accounts? Most landlords accept multiple accounts, but ask the applicant to provide statements for all of them. The aggregate balance across all accounts is the relevant figure.
What if the bank statement is in a foreign currency? Convert the statement to USD using the bank’s posted exchange rate. Most US landlords require the statement in USD; international applicants often need to convert before submitting.
What about credit-card statements alongside the bank statement? Most landlords do not require credit-card statements for rental applications. Lenders often do, for mortgage underwriting. Each workflow has its own documentation rule.
For related reading
On the broader clusters, see the complete MCC guide for the merchant category code system, and the complete US bank payment rails guide for ACH and wire transaction codes. The expanded bank statement anatomy pairs naturally with this hub.
Easy Statement Sheet reads bank-statement and credit-card-statement PDFs into a clean four-column output. The first three statement conversions are free, no card required. Plans start at $15 per month.
Practical walkthroughs
Consider an applicant in New York City applying for a $3,500/month apartment. The landlord requests two months of bank statements plus proof of income. The applicant converts each PDF to a four-column spreadsheet. The conversion output shows monthly deposits of $8,500 from payroll, an average ending balance of $4,200, and no unusual activity. The landlord approves with standard lease terms. No additional documentation is needed.
Consider an applicant in San Francisco applying for a $4,200/month apartment. The landlord pulls two months of bank statements and one month of credit-card statements. The bank statement shows monthly payroll deposits of $9,500 and a credit-card statement with $3,200 of monthly recurring expenses including rent in the prior city. The landlord approves with a standard deposit and first-month rent upfront.
Consider an international applicant in Boston applying for a $3,800/month apartment. The applicant does not have a US credit history. The landlord relies on the bank statement alone, which shows $11,000 in monthly international transfers and an average ending balance of $7,500. The landlord approves with a higher deposit (three months rent) given the lack of US credit history.
Consider a self-employed applicant in Chicago applying for a $2,800/month apartment. The applicant provides two months of bank statements and the most recent tax return. The bank statement shows fluctuating income averaging $6,500 per month with a stable ending balance. The tax return confirms annual income of $82,000. The landlord approves with a higher deposit given the irregular cash flow pattern.
Consider a couple applying together for a $5,200/month apartment. Each applicant provides two months of bank statements. The combined monthly income is $14,000 from both paychecks, and the combined ending balance averages $9,800. The landlord approves with standard lease terms based on the combined income exceeding the rent threshold of three-to-one.
Consider an applicant with a recent credit event. The landlord pulls two months of bank statements and sees the recent credit event reflected as a larger-than-usual outflow. The applicant explains the event was a one-time medical procedure. The landlord requests additional documentation showing the event was paid in full. The applicant provides a letter from the medical provider. The landlord approves.
Consider a senior applicant on a fixed income. The landlord pulls two months of bank statements showing monthly Social Security deposits of $2,800. The bank statement also shows a stable ending balance averaging $18,000. The landlord approves based on the consistent income and the verification of long-term source.
Common follow-up questions
How many months of bank statement does a typical landlord request? Most landlords request two months. Some request three. For high-end rentals or competitive markets, the statement period may extend to six months. For international applicants, a longer statement history may be requested.
What if the applicant does not have a US bank account? International applicants should provide statements from their home-country bank, with translation and currency conversion. Most landlords accept this with additional documentation. The first three statement conversions are free, no card required.
What if the bank statement shows irregular income? Self-employed applicants often have irregular income. The landlord will usually request additional documentation such as tax returns or 1099 forms to verify annualized income stability. The bank statement still shows point-in-time cash flow.
What about credit-card statements alongside the bank statement? Most landlords do not require credit-card statements for rental applications. Lenders often do, for mortgage underwriting. Each workflow has its own documentation rule. Easy Statement Sheet handles both statement types in the same conversion tool.
What if the application is denied based on the bank statement? Most denials are based on insufficient income relative to rent, large unexplained outflows, or insufficient ending balance. The applicant can ask for the specific reason and provide additional documentation to address the concern.
What about the security deposit and first month rent? Most landlords request first month rent plus a security deposit equal to one month rent. High-end rentals or competitive markets may require two months deposit. The applicant’s bank statement should show enough balance to cover both the deposit and first month rent upfront.
How long does the landlord verify the bank statement? Most landlords take 24-72 hours to verify the bank statement against the rest of the application. Some landlords take up to a week for thorough verification. The verification includes the variance check on the running balance and the merchant category code review.
Does the landlord need the original PDF or the conversion output? Most landlords accept either. The conversion output is usually easier to scan because the four-column format highlights the key data. Some landlords keep both on file: the original PDF as backup and the conversion output as the primary review material.
From Bank Statement to QuickBooks-Ready File
That manual cleanup you just read about? This tool skips it. Turn your PDF into QBO for QuickBooks without storing your data anywhere.
Start Converting