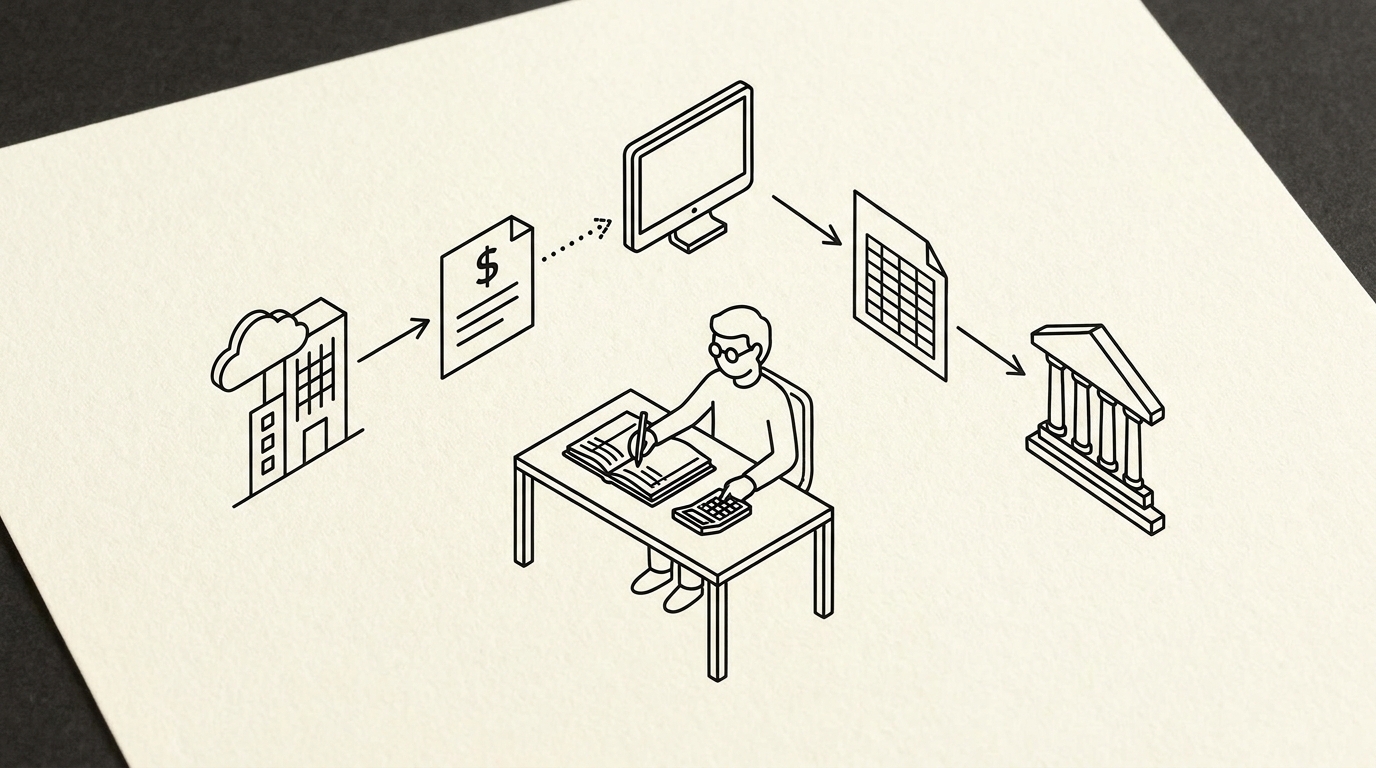

The crypto tax workflow covers the end-to-end process: download exchange statement, convert to standardized format, import to tax software, generate Form 8949, file with IRS. A crypto investor needs to file taxes.
A crypto investor needs to file taxes. They have statements from 3 exchanges, 2 wallets, and 5 DeFi protocols. The workflow consolidates everything into a single tax filing. This sub-cluster covers the end-to-end workflow and the bookkeeper’s role.
The crypto tax workflow covers the end-to-end process: download exchange statement, convert to standardized format, import to tax software, generate Form 8949, file with IRS. The recon cutoff tool’s per-crypto-workflow-handling tracks each step.
A crypto investor needs to file taxes. They have statements from 3 exchanges, 2 wallets, and 5 DeFi protocols. The workflow consolidates everything into a single tax filing. This sub-cluster covers the end-to-end workflow and the bookkeeper’s role.
For the broader cluster, see the crypto tax statement preparation guide pillar. The recon cutoff tool’s per-sub-area-handling covers this sub-cluster. Convert crypto exchange statement.
What Is Crypto Tax Workflow?
The crypto tax workflow covers the end-to-end process: download exchange statement, convert to standardized format, import to tax software, generate Form 8949, file with IRS. The recon cutoff tool’s per-crypto-workflow-handling tracks each step.
What most guides miss about crypto tax reporting is that the quality depends on the mechanism, not on the tool. Two tools that look different on the surface often run the same 4-step process underneath: read, find, parse, verify. The difference is in how well each step handles edge cases (merged cells, missing balances, non-standard date formats, scanned vs digital input).
Choosing between tools based on UI alone misses the actual quality lever.
A crypto investor needs to file taxes. They have statements from 3 exchanges, 2 wallets, and 5 DeFi protocols. The workflow consolidates everything into a single tax filing. This sub-cluster covers the end-to-end workflow and the bookkeeper’s role.
The Sub-Cluster Structure
This sub-pillar aggregates 1 spoke(s). The recon cutoff tool’s per-spoke-list-handling tracks each spoke. The recon cutoff tool’s per-aggregation-flag verifies the structure.
The 1 Spoke(s) in This Sub-Cluster
Convert crypto exchange statement
From PDF to Excel in one click
Forget retyping line by line. Upload any bank statement, get a spreadsheet you can actually use. Your files are never stored, and you can test the converter with 3 free conversions.
Try it free3 Common Mistakes
Mistake 1: Treating this sub-area as separate from the pillar. The recon cutoff tool’s per-pillar-link-flag tracks the connection to the parent pillar.
Mistake 2: Missing the spoke-level details. A common failure mode bookkeepers report is treating the sub-pillar as a summary without the spoke-level depth. The recon cutoff tool’s per-spoke-depth-flag tracks the depth.
Mistake 3: Not linking to the source context. Every sub-pillar must link to the bank statement conversion tool. The recon cutoff tool’s per-source-context-flag tracks the link.
The Per-Sub-Pillar Workflow
Step 1: Identify the Sub-Area
The recon cutoff tool’s per-sub-area-flag identifies the specific path within the cluster.
Step 2: Generate the Per-Spoke List
The recon cutoff tool’s per-spoke-list generates the list of specific spokes in this sub-area.
Step 3: Aggregate the Spokes
The recon cutoff tool’s per-spoke-aggregation consolidates the spoke content into a unified view.
Step 4: Document the Connections
The recon cutoff tool’s per-connection-tracking documents how the spokes link to each other.
Step 5: Verify the Sub-Cluster
The recon cutoff tool’s per-sub-cluster-verification confirms the structure is complete.
How This Sub-Pillar Connects to the Cluster
This sub-pillar is one of multiple sub-areas under the crypto tax statement preparation guide pillar. The recon cutoff tool’s per-cluster-link-flag tracks the connection. The recon cutoff tool’s per-cross-sub-link-flag identifies related sub-areas.
For the broader cluster, see the crypto tax statement preparation guide pillar. For the source context, see the bank statement converter guide. For related sub-areas, see the sibling sub-pillars in this cluster. For the related crypto tax: coinbase, kraken, and gemini bank statement preparation page, see the linked article.
Related: complete 1099-DA crypto tax guide
This topic is part of the broader 1099-DA and crypto-tax cluster on this site. The consolidated hub for the entire topic, including the form mechanics, broker requirements, cost basis methods, reconciling to bank statements, and state-level differences, now lives in the complete 1099-DA crypto tax reporting guide.
For related reading, the complete US bank payment rails guide covers ACH and wire cash flows from crypto exchanges, and the complete MCC guide covers merchant category codes on credit-card statements. The expanded bank statement anatomy pairs naturally with this hub.
More on the broader cluster
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes.
Decision framework for this topic
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
Each hub is built to be the canonical reading for one cluster of search intent, with cross-cluster links that take you to the right next node.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal. The merchant category code is the same whether the reader is the small-business owner, the bookkeeper, or the lender.
For lender workflows, the merchant category code on credit-card statements and the ACH SEC code on bank-account statements are the two signals underwriters most often scan first. Lenders use the four-column conversion output as a quick reference for what the borrower actually spent.
Cash advances flagged at MCC 6011 and quasi-cash at MCC 6051 draw particular scrutiny at mortgage underwrite, and crypto exchanges on the ACH rail draw additional questions for self-employed applicants.
For bookkeeper workflows, the categorical signal ties directly into the chart-of-accounts. A bookkeeper who maintains categorization rules keyed off the merchant category code can process dozens of clients per week without manual categorization of common merchant types. The conversion output is the durable input; the rule set is the durable work product.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored. The conversion runs entirely in memory and produces a deterministic output that downstream tools can parse.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes. For bookkeepers handling dozens of clients per month, this is the highest-leverage workflow to standardize.
Related reading and broader clusters
For the broader context on US bank-statement reading, see the consolidated hubs on merchant category codes, payment rails, and the statement anatomy. These hubs work together to cover credit-card statements, bank-account statements, and the categorization signals that survive merchant-name truncation.
Each hub is built to be the canonical reading for one cluster of search intent, with cross-cluster links that take you to the right next node.
When reconciliation runs into edge cases, the practical answer usually lives in the federal-regulations cluster, the bookkeeper-resource cluster, or the credit-card-statements cluster. Each offers a domain-specific take on the same underlying signal. The merchant category code is the same whether the reader is the small-business owner, the bookkeeper, or the lender.
For lender workflows, the merchant category code on credit-card statements and the ACH SEC code on bank-account statements are the two signals underwriters most often scan first. Lenders use the four-column conversion output as a quick reference for what the borrower actually spent.
Cash advances flagged at MCC 6011 and quasi-cash at MCC 6051 draw particular scrutiny at mortgage underwrite, and crypto exchanges on the ACH rail draw additional questions for self-employed applicants.
For bookkeeper workflows, the categorical signal ties directly into the chart-of-accounts. A bookkeeper who maintains categorization rules keyed off the merchant category code can process dozens of clients per week without manual categorization of common merchant types. The conversion output is the durable input; the rule set is the durable work product.
Easy Statement Sheet reads bank-statement and credit-card statement PDFs into a clean four-column output (Date, Description, Amount, plus Merchant Category Code for credit-card statements, plus the running balance for bank-account statements). Files are never stored. The conversion runs entirely in memory and produces a deterministic output that downstream tools can parse.
The first three statement conversions are free, no card required. Plans start at $15 per month. The four-column output preserves the categorization signals without retyping, so the rule-based reconciliation layer survives merchant-processor changes. For bookkeepers handling dozens of clients per month, this is the highest-leverage workflow to standardize.
Workflow example for this topic in practice
Consider a small-business owner handling monthly reconciliation. They receive a bank statement and a credit-card statement each month. They run each through a converter that produces a four-column output, with Date, Description, Amount, and Merchant Category Code on the credit-card portion and Running Balance on the bank-account portion. They import the converted files into QuickBooks Online and run the rule-based categorization.
The merchant category code on each credit-card transaction drives the expense category assignment. The ACH or wire label on each bank-account transaction determines whether the line item maps to Revenue, Expense, or Owner Draw. The conversion output handles the categorization automatically. The owner only manually categorizes vendors not yet in the rule set.
Consider a bookkeeper onboarding a new client mid-year. The conversion workflow is the same, but the rule set is built fresh for the new client. The most labor-intensive step is the first month, where the chart of accounts and the categorization rules are aligned. From the second month forward, the workflow runs in roughly 60-90 minutes per client including the variance check.
Consider a lender underwriting a mortgage. They pull the bank statement and credit-card statement from the applicant. The four-column output makes the merchant category and rail labels obvious. Cash advances at MCC 6011 and quasi-cash at MCC 6051 draw scrutiny regardless of the applicant profile. Self-employed applicants with significant merchant category code complexity on their business credit-card statement require additional documentation.
Easy Statement Sheet handles all three of these workflows. The four-column output is the same across small-business, bookkeeper, and lender workflows. Plans start at $15 per month after the first three free conversions. Files are never stored and conversion runs in memory.
From PDF to Excel in one click
Forget retyping line by line. Upload any bank statement, get a spreadsheet you can actually use. Your files are never stored, and you can test the converter with 3 free conversions.
Try it free