An IRS bank statement audit response requires 7 years of statements organized by year and account, with a reconciliation summary that ties each statement to
The short answer: organize the 7 years of statements, create a reconciliation summary that ties the deposits to the reported income, document any large or unusual transactions, and respond to the auditor within 30 days. Most bank statement audits are resolved with documentation, not penalties.
TL;DR. For an IRS bank statement audit response: (1) gather 7 years of statements organized by year, (2) reconcile the deposits to the reported income, (3) document any large or unusual transactions, (4) respond to the auditor within 30 days. The 4 most common audit triggers: deposits that don’t match reported income, large cash deposits, undisclosed accounts, and inconsistent monthly deposits. The 3 best practices: keep 7 years of statements, document large transactions as they happen, separate personal and business accounts.
What Is a Bank Statement Audit
A bank statement audit is a request by the IRS (or other tax authority) to review the bank statements that support a tax return. The audit may be:
- Correspondence audit: A letter requesting specific documents, typically resolved by mail. The most common type of audit.
- Office audit: A visit to the IRS office to review documents in person. Less common.
- Field audit: A visit to the taxpayer’s home or business to review documents. The most comprehensive type of audit.
Bank statement audits are typically triggered by:
- Deposits that don’t match reported income: The IRS receives 1099 forms and 1099-K reports from banks and payment platforms. If the deposits on the bank statement don’t match the income reported on the tax return, the IRS may audit.
- Large cash deposits: Cash deposits over $10,000 trigger a Currency Transaction Report (CTR) at the bank. The IRS receives CTRs and may audit to verify the source of the cash.
- Undisclosed accounts: The IRS has access to third-party reporting (1099, 1099-K, 1098). If an account is missing from the return, the IRS may detect and audit.
- Inconsistent monthly deposits: A self-employed taxpayer with stable income but inconsistent monthly deposits may be audited to verify the actual income.
The 4-Step Response Process
4 steps to respond to a bank statement audit, in sequence:
Step 1: Gather 7 years of statements (1-2 hours). Download 7 years of statements from every account: checking, savings, business, credit card. Save them in a single folder, organized by year and account. For statements older than the online banking limit (typically 24 months), contact the bank to request copies. The fee is typically $5-25 per statement. The processing time is 5-10 business days.
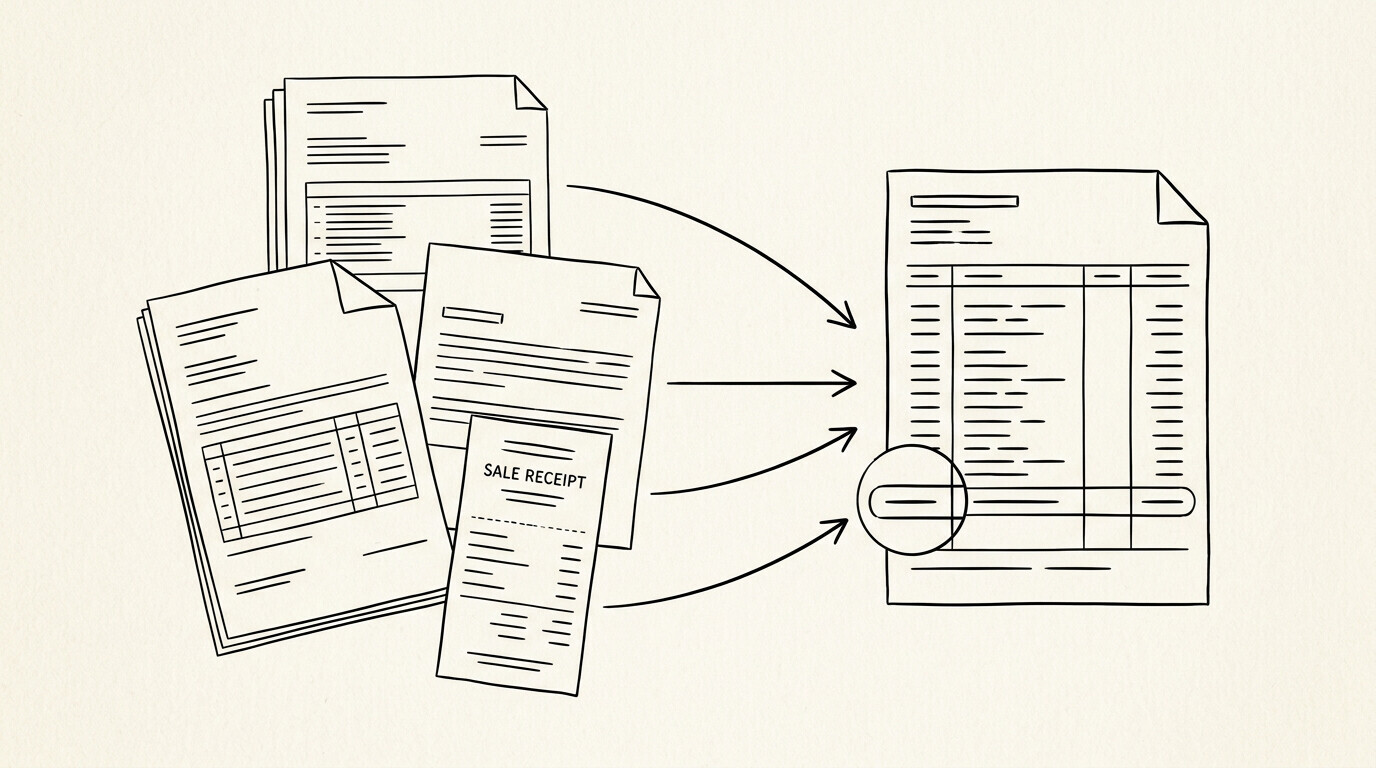
Step 2: Reconcile deposits to reported income (2-4 hours). For each year, sum the deposits across all accounts. Compare to the income reported on the tax return. The deposits should equal the reported income (plus any non-income deposits: loan proceeds, transfers, refunds, asset sales). The reconciliation summary should explain any difference.
The reconciliation format: a one-page summary per year, with the deposits, the reported income, the difference, and the explanation for the difference. The format should be clear and easy for the auditor to follow.
Step 3: Document large or unusual transactions (1-2 hours). For any deposit over $5,000, document the source. The source may be: a customer payment, a loan, a transfer from another account, an asset sale, a gift, or a refund. The documentation may be: an invoice, a loan agreement, a transfer receipt, a sale contract, a gift letter, or a refund notice. The auditor wants to verify that the deposit is not unreported income.
Step 4: Respond to the auditor (1-2 hours). Submit the statements, the reconciliation summary, and the documentation to the auditor. The response is typically by mail or through the IRS online portal. The response is due within 30 days of the audit notice. If 30 days is not enough, request an extension (typically 30 additional days).
The response should be professional, complete, and well-organized. The auditor is more likely to close the audit quickly if the response is clear and addresses the specific questions asked.
Turn PDF Bank Statements Into Workable Spreadsheets
Your bank statement is a mess of numbers, but your books shouldn't be. Use our converter to get Excel, CSV, or QBO files — ready for QuickBooks.
Try It Free Now4 Common Audit Triggers
4 triggers that lead to bank statement audits:
1. Deposits that don’t match reported income. If the deposits total $300K but the reported income is $200K, the $100K difference is unexplained. The IRS will ask for documentation of the $100K. The fix: maintain a reconciliation summary that ties the deposits to the reported income, with explanations for any difference.
2. Large cash deposits. Cash deposits over $10K trigger a CTR. The CTR goes to FinCEN (Financial Crimes Enforcement Network), which shares the data with the IRS. The IRS may audit to verify the source of the cash. The fix: document the source of all cash deposits (customer payment, loan, transfer) and keep the documentation with the statement.
3. Undisclosed accounts. The IRS has access to all bank accounts through third-party reporting (1099-INT for interest, 1099 for other income, 1099-K for payment platforms). If an account is not on the tax return, the IRS may detect and audit. The fix: include all accounts on the tax return, even those with no transactions.
4. Inconsistent monthly deposits. A self-employed taxpayer with $25K in January, $5K in February, and $30K in March may be audited to verify the actual income. The inconsistency may be seasonal (taxable), one-time deposits (loans, transfers), or unreported income. The fix: maintain a year-end reconciliation that explains the seasonal pattern and identifies the one-time deposits.
The 3 Best Practices for Audit Defense
3 best practices that make audit defense easier:
1. Keep 7 years of statements. The IRS retention requirement is 3-7 years. The safe practice: keep 7 years. The cost is minimal ($0.10/month cloud storage); the benefit is significant. Without the statements, the auditor may assess additional tax based on the deposits, and the taxpayer has no documentation to dispute the assessment.
2. Document large transactions as they happen. When a large deposit or withdrawal occurs, document the source or destination in a notes column in the accounting software. The documentation is much easier to do in real-time than to reconstruct 3 years later during an audit. The fix: add a “Notes” or “Source” column to the accounting software, and document every transaction over $5K.
3. Separate personal and business accounts. Mixing personal and business in one account creates audit risk. The auditor cannot tell which transactions are business income, which are personal, and which are transfers. The fix: open a separate business account and use it only for business transactions. The cost is minimal ($0-20/month for a basic business account).
What to Do If You Get an Audit Notice
If you receive an audit notice, the 5 steps to take:
- Read the notice carefully: The notice specifies which tax year, which accounts, and which documents are requested. The request may be for all statements, specific months, or specific transactions.
- Don’t panic: Most audits are resolved with documentation. Only a small percentage of audits result in additional tax or penalties. The fix: stay calm and start gathering the documents.
- Gather the documents: Download the statements from online banking. Contact the bank for older statements if needed. Organize by year and account.
- Consider professional help: A CPA or tax attorney can help prepare the response, especially for complex situations. The cost is typically $500-2000 for an audit response, much less than the potential tax and penalties if the response is inadequate.
- Submit the response: Submit the documents, the reconciliation summary, and the documentation to the auditor. The response is due within 30 days.
After the Audit
The 3 possible outcomes of an audit:
1. No change. The auditor reviewed the documents and confirmed the tax return is correct. This is the most common outcome. The audit is closed.
2. Agreed change. The auditor proposed a change to the tax return (typically additional tax owed). The taxpayer agrees. The taxpayer pays the additional tax plus interest (and possibly penalties).
3. Disagreed change. The auditor proposed a change. The taxpayer disagrees. The taxpayer can appeal through the IRS Appeals process, or ultimately through the Tax Court.
Most bank statement audits result in outcome 1 (no change) or outcome 2 (agreed change with documentation). The disagreements are rare and typically involve complex situations where the documentation is unclear or the tax law interpretation is disputed.
A common failure mode bookkeepers report is treating this as a single operation rather than a chain of dependent steps. The temptation is to find a tool that ‘just works’ and stop investigating the mechanism. The result is a wrong-fix cycle: the tool gives partial output, the bookkeeper spends 30+ minutes troubleshooting, the fix is for the wrong step, and the same error recurs on the next statement. The fix: identify which step failed and apply the right intervention to that step.
The Bigger Picture
Bank statement audits are a routine part of the tax system. The IRS audits approximately 1% of individual returns each year, and bank statement audits are a small fraction of those. The most common audit triggers are the 4 listed above, and all 4 are preventable with good record-keeping.
The investment in good record-keeping (keeping 7 years of statements, reconciling monthly, documenting large transactions) is small compared to the cost of an unprepared audit response. The 4-step response process takes 5-10 hours; the prevention takes 2-3 hours per year (30 minutes per month for reconciliation, plus the monthly statement download).
For the underlying conversion step, see the bank statement converter page. For the tax prep workflow, see the how to organize for tax preparation guide. For the 7-year retention rule, see the IRS publication 552 reference. For the broader bank statement glossary, see the bank statement glossary.
From Bank Statement to QuickBooks-Ready File
That manual cleanup you just read about? This tool skips it. Turn your PDF into QBO for QuickBooks without storing your data anywhere.
Start Converting